How One Navy Servicewoman Used Her VA Loan to Build Six-Figure Wealth
See how one Navy servicewoman used her VA loan to buy with zero down, collect six figures in tax-free equity, and reset her wealth clock moving back east.
She was told not to buy. Her peers said it wasn’t worth it, she’d be stationed in San Diego for only a few years, the market was expensive, and renting was “just easier.” She almost listened.
Instead, she attended a Heroes Star VA homebuyer seminar, learned what her VA loan benefit actually made possible, and decided to bet on herself. Four-plus years later, she walked away from the sale of her San Diego home with over six figures in tax-free equity, her escrow check in hand, and her VA loan fully available to use again.
That’s not luck. That’s VA loan wealth building in action. That’s what happens when a servicewoman gets the right education at the right time and takes action. This guide walks through exactly how she did it step by step so you understand the playbook and can run it yourself. Whether you’re currently stationed in San Diego, eyeing your first home, or already a homeowner wondering what your options are, this is the real-world proof that your VA loan benefit is one of the most powerful wealth-building tools you will ever have access to.
Why Most Service Members Leave This Benefit on the Table
Most service members earned one of the most powerful wealth-building tools in America and never use it. That’s not an opinion. About 1 in 3 veterans reported receiving little to no education about the VA loan benefit during or after their military service, and 30% remain unsure if they even qualify. Think about that. You served, you qualified, and no one told you what you actually had. The real enemy here isn’t the VA.
It’s three things working together: peer pressure, myths, and a flat-out lack of education. Understanding VA loan wealth building starts with recognizing that your VA home loan is not simply a financing option. It’s an opportunity to build equity while establishing a foundation for long term financial security.
The “Just Rent” Trap
The servicewoman whose story anchors this guide almost made the same mistake. Her peers told her what a lot of service members hear, the market’s too expensive, you’re only here for a few years, renting is just easier. That’s the “just rent” trap, and it costs people six figures. Many veterans report they either never heard about the benefit, assumed they would not qualify, or believed a VA loan was slower and weaker in competitive markets and misconceptions from peers, agents, and lenders can reinforce those incorrect assumptions for years.
The Myth That It Only Works Once
One of the most damaging myths is that the VA loan is a one-time deal. A Navy Federal survey found that even though a VA loan benefit can be used more than once, 50% of active-duty service members and 31% of veterans believed the benefit could only be used once. That single misunderstanding stops people from thinking about their benefit as a long-term wealth strategy which is exactly what it is.
What Changes When You Get Educated
She didn’t talk herself out of it. She attended a Heroes Star VA homebuyer seminar, learned what her benefit actually covered, and made a decision that changed the trajectory of her financial life. Education was the turning point not luck, not timing, not a hot market. “The biggest barrier to veterans using their benefit is education,” and that’s exactly the gap Heroes Star was built to close.
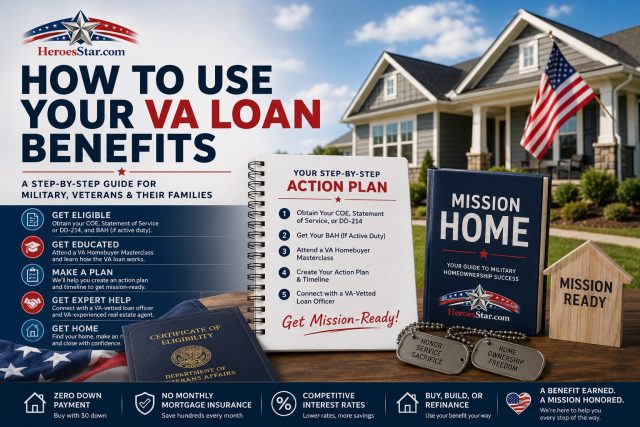
The next section breaks down precisely how she structured the purchase and why she walked away from closing without spending a dollar.
The VA No-No: How She Bought a San Diego Home With Zero Out of Pocket
She didn’t bring a cashier’s check to closing. She brought an empty wallet and left with keys and a check made out to her. This is where VA loan wealth building begins: reducing upfront purchase expenses while positioning yourself to benefit from future home equity. That is what a properly structured VA transaction can do, and it has a name: the VA no-no.
What the VA No-No Actually Means
The term is simple. No down payment. No closing costs paid by the buyer. The VA loan program already eliminates the down payment requirement entirely. The closing cost piece that’s where smart negotiation and a knowledgeable agent close the gap. The VA allows sellers to pay all loan related closing costs, and sellers can contribute up to 4% of the purchase price toward additional expenses through seller concessions. When you structure the offer correctly, VA loans allow a seller to pay all of the closing costs for the buyer. That 4% can also go further than most people realize, it can cover prepaid property taxes and homeowner’s insurance, pay off debts to help a buyer qualify, cover the VA funding fee, or buy down the interest rate with discount points. That last one matters. A skilled agent doesn’t just negotiate the price they structure the offer to extract maximum value from those concessions.
From Seminar to Keys
She walked into a Heroes Star VA homebuyer seminar without a clear path forward. She walked out with a plan. At that seminar, she learned exactly what documents she needed to unlock her benefit. A statement of service is required for all active duty service members as a way to verify their eligibility for VA home loan benefits. Her Certificate of Eligibility confirms she has VA loan benefits, while the Statement of Service confirms she is still serving and tells the lender when she expects to separate. Two documents. That’s it.
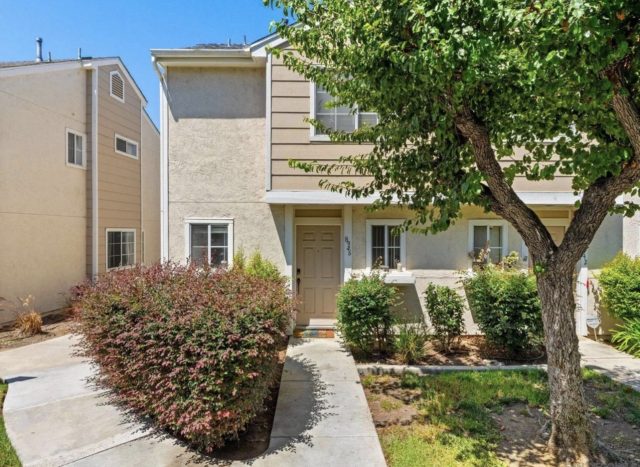
Once she had those in hand, she could get pre-approved and move. The offer was structured as a VA no-no. The seller paid closing costs. Her deposit the earnest money she put down to make the offer came back to her at the closing table because the seller concessions covered more than the actual costs. She received the keys to her San Diego home and a check in the same sitting. That moment right there is what education makes possible. No one handed it to her, she learned it, she claimed it.
Next up: what she did with that home once she had it.
The Roommate Strategy: Turning a Home Into a Cash-Flow Asset
Buying with zero out of pocket was the first move. The second move is what separated her from every service member still writing a rent check to a landlord. She got a roommate. Simple. Unglamorous. Wildly effective.Her roommate strategy became another important part of VA loan wealth building, helping offset monthly housing expenses while she continued building equity,
BAH Is the Engine Use It
Something most people overlook: BAH is an allowance designed to offset the cost of housing when you do not receive government-provided housing. That means the government is already paying toward your housing every single month. When you rent, that money goes to someone else’s mortgage. When you own, it goes toward yours and you control what happens next. San Diego BAH rates for enlisted members range from roughly $2,748 to over $4,000 per month depending on rank and dependent status, real money that hits your account whether you spend it wisely or not. She spent it wisely. By bringing in a fellow service member as a roommate, she covered close to half her monthly mortgage payment. Her BAH handled the rest. Her out-of-pocket housing cost? Nearly zero month after month, for over four years.
From Liability to Asset
That’s the shift most people miss. A mortgage looks like a bill. With the right structure, it performs like an investment from day one. She wasn’t a landlord running a rental empire. She just made one smart decision: stop paying for space she wasn’t using. The roommate covered their share, her BAH covered hers, and the equity clock started ticking the moment she got those keys. This reality pushes many active-duty members toward homeownership, where their monthly payment builds equity rather than enriching a landlord. She understood that before most of her peers did. That equity built quietly over four years while she focused on her career is what the next section is about.
Selling Smart: The VA Homeowner Masterclass and the Tax-Free Equity Exit
Buying smart was only half the mission. Selling smart is where the real money moves. When the time came to transition out of the military, get married, and head back east, she didn’t just call the first agent she found on Zillow. She came back to the same place she started: a Heroes Star masterclass, this time the VA Homeowner Masterclass.
From there, she got connected to a local VA Heroes Agent in San Diego, Johnny Perez with Compass, who knew exactly how to position her property, price it to attract serious buyers, and close fast.
The result: a quick sale at top dollar. She walked away with six figures in equity. Her successful home sale demonstrates how VA loan wealth building can create financial opportunities when military members transition to civilian life or relocate to another state.
Why the Exit Was Tax-Free
Here’s the part most people never hear about, and it’s worth slowing down for. The home sale tax exclusion also known as the Section 121 exclusion allows individuals who sell their principal home to exclude from taxable income up to $250,000 of the gain, or up to $500,000 if they are a married couple filing a joint return. She was newly married. That means up to half a million dollars in profit, completely sheltered from federal capital gains tax. The qualification rule is straightforward. To qualify, you must own and occupy the home as your principal residence for at least two of the five years before you sell it.
She had lived there for four-plus years. She cleared that bar with room to spare. Your residence is one of the few assets that can be sold for a gain without creating tax liability the IRS rules allow $250,000 per person of gain to be excluded from income. Most investors never see a deal structured this cleanly. She did, because she was educated before she ever signed a listing agreement. That education, the masterclass, the certified agent, the plan is the difference between leaving money on the table and leaving San Diego with a six-figure savings account and a VA loan ready to use again.
What Comes Next: Resetting the Clock and Buying Again Back East
Her San Diego chapter is closed. But her VA loan story? It’s just getting started. Here’s what this section hands you: a clear picture of how entitlement restoration works, a look at bonus entitlement for veterans who want to hold a property while buying a new one, and a direct path to your own next move through Heroes Star.
Your Benefit Comes Back Fully
When she sold that San Diego home, paid off the VA loan at closing, and walked away with six figures in tax-free equity, her VA entitlement didn’t disappear. It reset. VA entitlement restoration gives you back the guaranty that was used on a prior VA loan so you can use it again on a new purchase. When you sell your home and pay off your VA loan in full, your entitlement is automatically restored you don’t need to apply for restoration in this case. She’s now heading back east with a healthy savings account and the same zero-down buying power she had four years ago. That’s not luck. That’s the system working exactly as it was designed.
What If You Want to Keep the Property and Buy Again?
Not every veteran sells before buying. Some want to keep the San Diego home as a rental and use their benefit on a new primary residence. That’s where **bonus entitlement** comes in, it’s what allows a veteran to carry two VA loans simultaneously, provided enough entitlement remains to cover the new loan in the county they’re buying in. The key factors are whether you’ve restored your entitlement by selling previous properties and paying off the loans, or whether you have sufficient remaining entitlement or bonus entitlement to purchase another home while keeping your current one. This is advanced territory. The numbers shift by county, loan size, and how much of your entitlement was originally used. It’s not a DIY calculation it’s a conversation worth having with a certified VA Heroes Agent or VA Lender before you do anything else.
Your Next Move Is One Masterclass Away
Her story proves that VA loan wealth building begins with education, preparation, and taking action. From purchasing her first home with Zero down to building six figures in equity, she transformed her VA benefits into a financial opportunity that will follow her into the next chapter of her life. It started with a webinar and a decision to show up and learn. The Heroes Star VA Masterclass is where that same conversation begins for you whether you’re buying for the first time, restoring entitlement after a sale, or exploring bonus entitlement to keep building your portfolio. The wealth isn’t in the waiting. Register for the next Heroes Star VA Masterclass, get mission ready, and let your benefit work as hard as you did to earn it.